

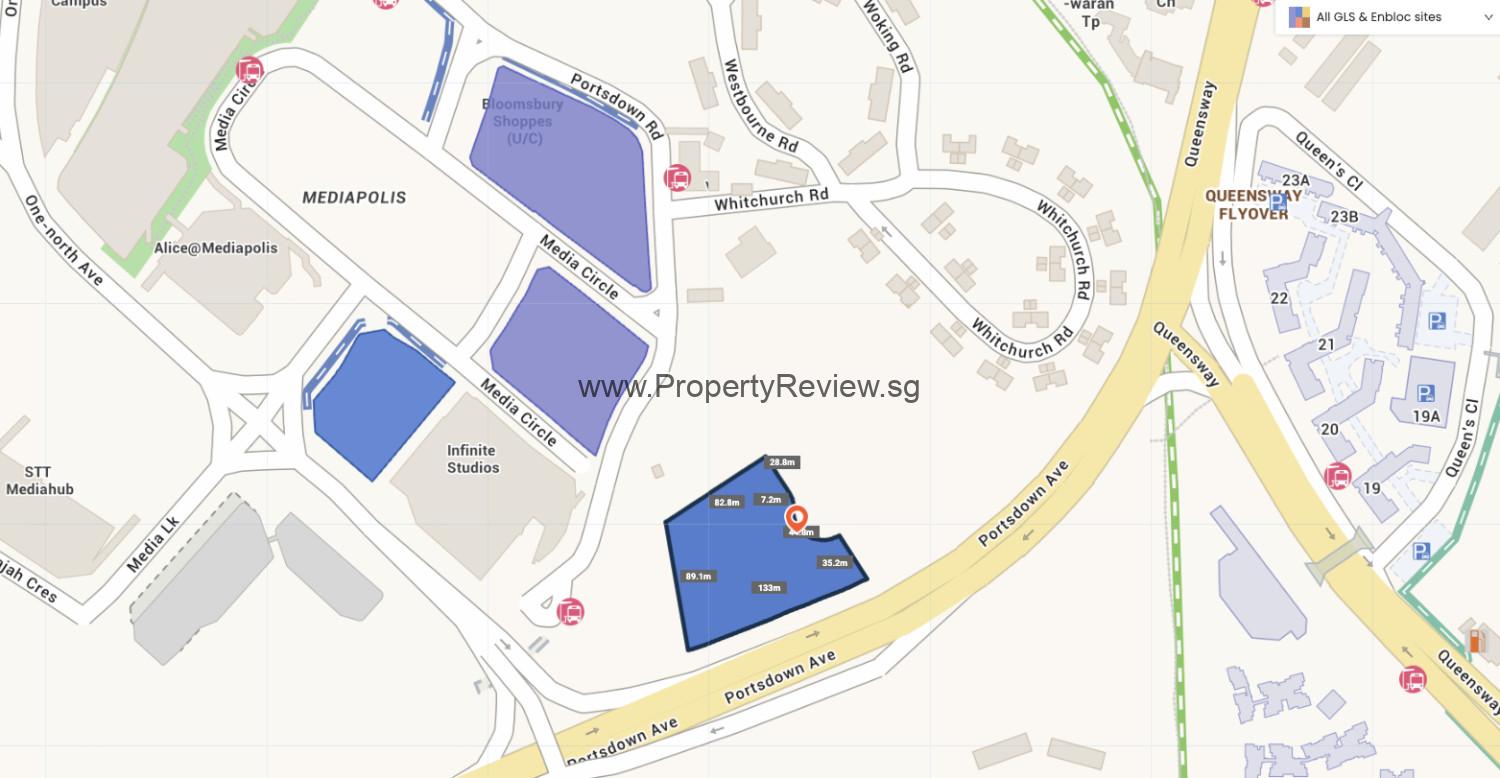
Closed on April 29 is the tender for Media Circle (Parcel B), a Government Land Sale (GLS) site situated in the one-north neighborhood. A URA press statement states that the site did not draw any offers.
The 99-year leasehold land is first level commercial, with residential zoning. About 107,936 square feet allow it to possibly produce 500 residential units.
Launched for tender in November, Media Circle (Parcel B) property and its adjacent site, Media Circle (Parcel A), Last month Parcel A was given to a group consisting of Qingjian Realty, Forsea Holdings, and minority investor Hoovasun Holding for $315 million ($1,037 psf ppr). Originally zoned for commercial development with residential at the first floor, the site can produce roughly 325 homes.
Prior to that, Qingjian Realty and Forsea Holdings paid $395.28 million or $1,191 psf ppr for another Media Circle GLS plot (the present location of Bloomsbury Residences). Launched earlier this month, the 358-unit Bloomsbury Residences sold total of 90 apartments (25.1%) at an average price of $2,474 psf over the launch weekend.
The CEO of Orangetee & Tie, Justin Quek, notes that remaining on hand at Slim Barracks Rise and Media Circle at One-North are inventories from previously started projects. Blossom by the Park has 19 out of 275 available according on URA monthly developer sales data as of March 2025; The Hill @ One-North still has 80 out of 142 apartments available. This on top of the existing Bloomsbury Residences balance units.
Based on Table 1, Media Circle (Parcel B) is the fourth GLS site opened for sale under tender in recent years. While the URA turned down the offer for a pure long-stay serviced apartment (SA2) site since it was judged too low, Wong Siew Ying, PropNex head of research and content, notes two of the other three plots were given awards.
Wong observes that various reasons could be the lack of interest in the Media Circle Parcel B site. Given that the site is next to the highway and further from the MRT station, the site attributes are particularly less appealing than the first two Media Circle sites awarded. Furthermore, since the changing US trade policies provide more major uncertainty to the global economy, developers might have been more cautious in obtaining development sites. She also notes that developers are probably more picky, choosing sites with great proximity to schools and the MRT station as well as amenities.
Tricia Song, CBRE head of research for Singapore and Southeast Asia, says “the one-north cluster is a non-mature estate without a significant residential catchment, but is a strategic research and development (R&D) hub for the biomedical science, infocomm technology, media, and engineering sectors”. “Young professionals and foreigners would find more appeal in living in such a location. Local owner-occupiers find this area less appealing without HDB upgraders in the locality and complete facilities including schools, childcare, big retail malls, hawker centres, and coffee shops.”
Upper Thomson Road (Parcel A) was the last GLS site whose demand was nil during a tender. Launched for sale in December 2023, the 99-year leasehold site, zoned for residential use with commercial at the first story, was tenderly closed June following. Among the 640 units the facility can produce are 100 long-stay serviced apartments.
Head of research at Knight Frank Singapore Leonard Tay thinks that the lack of offers for Media Circle (Parcel B) points to a more conservative attitude among developers in view of present global uncertainty brought on by US-led tariffs.
“Already most developers are mindful of development costs that constitute land and construction costs, as well as taxes, and might have stayed away from today’s tender to keep their powder dry for other sites in established residential areas rather than those in business zones,” he notes.
While juggling the effects of the continuous trade war on the domestic economy, Tay also notes that developers might have chosen to stop and evaluate the market for private residences.
Similar opinions hold true of Mark Yip, CEO of Huttons Asia. “The global tariffs may have made developers more circumspect and highly selective of the sites they want, even if the level of unsold units in the market has dropped to a new low of 18,270 units as of end-March 2025,” he remarks.


